Kalman Filtering·Series overview
Kalman Filtering
이 시리즈는 linear-Gaussian state-space model에서 Kalman filter의 prediction과 correction을 유도하고, covariance modeling·구현·diagnostics·LQG 연결까지 다룹니다. Probability와 state-space의 기초는 기존 문서에 연결하고 반복하지 않습니다.
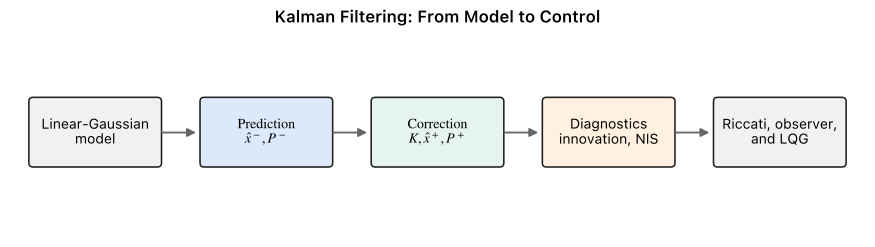
The series moves from the model and two recursive steps to implementation, diagnostics, and the Riccati–LQG connection.
이 시리즈가 답하는 질문
Linear-Gaussian model 아래에서 다음 recursion이 왜 exact posterior mean과 covariance를 주는지 설명하는 것이 도착점입니다.
공부를 시작할 때 실제로 막힌 질문은 다음과 같습니다.
- Posterior mean과 covariance를 Kalman gain으로 쓰는 식은 어디서 나오는가?
- Position만 측정했는데 velocity estimate가 함께 바뀌는 이유는 무엇인가?
- 와 은 단순한 tuning knob인가, model에서 나오는 covariance인가?
- Kalman covariance recursion과 LQR Riccati equation은 어떤 의미에서 dual인가?
강의 지도
| 강의 | 답하는 질문 | 핵심 결과 | 선행 연결 |
|---|---|---|---|
| L1 · The Linear-Gaussian Estimation Problem | 어떤 문제를 어떤 가정 아래 푸는가? | Gaussian belief의 closure | Bayes Filter · State-Space Realizations & Canonical Forms |
| L2 · Prediction | Dynamics가 mean과 covariance를 어떻게 옮기는가? | [[Bayes and Particle Filters L4 - The Bayes Filter#2. Prediction step 유도 | |
| L3 · Scalar Measurement Update | Prior와 scalar measurement를 어떻게 결합하는가? | L2 · Bayes Theorem | |
| L4 · Multivariate Measurement Update | Matrix gain은 왜 그 형태인가? | Positive Definiteness & Quadratic Forms | |
| L5 · The Complete Recursive Filter | 식을 안전한 구현으로 어떻게 옮기는가? | complete predict–correct loop | [[Kalman Filtering L1 - The Linear-Gaussian Estimation Problem |
| L6 · Noise Modeling and Diagnostics | 와 residual을 어떻게 다루는가? | innovation consistency·NIS | [[Kalman Filtering L5 - The Complete Recursive Filter |
| L7 · Riccati, Observers, and LQG | Observer·Riccati·LQR과 어떻게 연결되는가? | steady-state filter·separation principle | LQR, Riccati, and the Bellman Bridge |
읽는 순서와 선행 지식
| 이미 아는 것 | 이 시리즈에서 쓰이는 곳 | 연결 문서 |
|---|---|---|
| conditional distribution과 Bayes filter | Gaussian posterior와 predict–update 해석 | L4 · The Bayes Filter |
| state-space model | 와 observer 구조 | State-Space Realizations & Canonical Forms |
| covariance와 PSD matrix | uncertainty propagation과 covariance update | Positive Definiteness & Quadratic Forms |
| observability와 detectability | steady-state convergence 조건 | Controllability, Observability, Stabilizability, Detectability |
| Bellman·Riccati recursion | LQR–Kalman duality | LQR, Riccati, and the Bellman Bridge |
L1부터 순서대로 읽는 것이 기본입니다. Bayes filter notation이 낯설 때만 연결 문서로 돌아갑니다.
기호표
| 기호 | 의미 |
|---|---|
| hidden state | |
| known control input | |
| measurement | |
| dynamics, input, measurement matrices | |
| process noise, measurement noise | |
| noise covariance matrices | |
| measurement 전 prior mean과 covariance | |
| measurement 후 posterior mean과 covariance | |
| innovation 또는 measurement residual | |
| innovation covariance | |
| Kalman gain |
Superscript 와 는 부호가 아니라 같은 시각 에서 measurement를 반영하기 전과 후를 구분합니다.
이 시리즈에서 뺀 것
- Probability·state-space·PSD의 기초 재강의 — 기존 문서와 중복되므로 링크만 둡니다.
- Continuous-time Kalman–Bucy filter — discrete implementation과 CARE의 경계를 흐리지 않도록 분리합니다.
- EKF·UKF — nonlinear approximation이므로 exact linear filter를 완성한 뒤 별도 학습 대상으로 둡니다.
- Smoothing — filtering과 conditioning 대상이 다르므로 별도 주제입니다.
- Information filter와 square-root filter — large-scale 또는 numerical linear algebra 심화입니다.
- SLAM과 data association — estimator 하나보다 큰 inference system입니다.
목적성
Kalman filter는 robot state estimation에서 model prediction과 sensor correction을 결합하는 기본 구조입니다. 동시에 covariance propagation, observability, Riccati equation, LQG를 하나의 흐름으로 연결합니다. Formula lookup이 아니라 model assumption과 diagnostic residual을 읽을 수 있는 수준을 목표로 합니다.
더 읽을거리
- Probabilistic Robotics (Sebastian Thrun, Wolfram Burgard, Dieter Fox) — Bayes filter 안에서 Kalman family의 위치를 볼 때
- Optimal State Estimation (Dan Simon) — implementation과 nonlinear extensions를 더 깊게 볼 때
- Stochastic Processes and Filtering Theory (Andrew Jazwinski) — convergence와 stochastic systems 이론이 필요할 때
Related: Bayes Filter · LQR and the Riccati Equation · Sensors vs Simulator in Robot RL